

Hospitality
Between 2020 and 2023, Asia-Pacific hotels went through closures, an uneven recovery and sharp rate rises in some markets, leaving clear lessons for hotel owners.
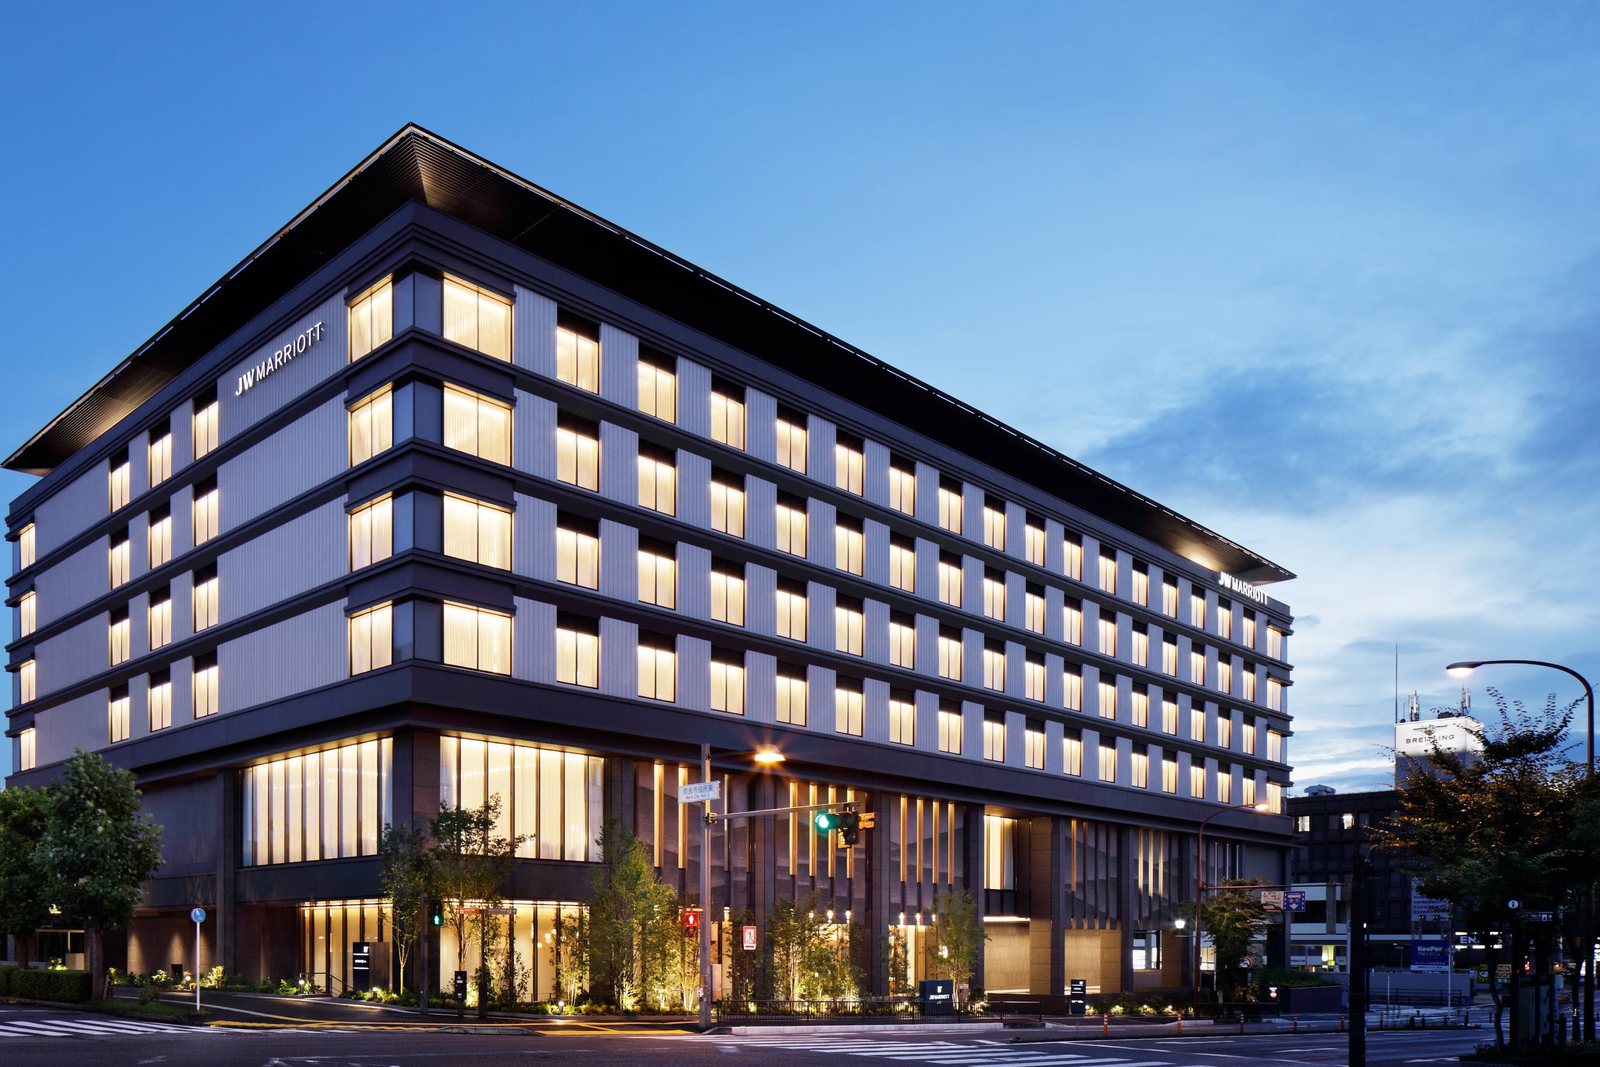
Covid-19 was a major shock to the hotel industry. Looking back at 2020–2023 through the information Rubix Navigation followed, the journey had three stages: closure, an uneven recovery and sharp rate rises in some markets.
At the worst point, around half of Marriott International’s hotels in Asia-Pacific outside mainland China were closed; by July 2020 around 20 per cent had still not reopened. Even so, Marriott International opened the 158-room JW Marriott Hotel Nara, its 800th hotel in the region, and at the time aimed to open 40 to 50 hotels that year. By late 2020 Accor had opened 76 hotels in Asia, with another 32 planned before year end. Projects close to completion were hard to stop: opening decisions depended on investment progress and local conditions, not only on immediate demand.
By late March 2022, according to ForwardKeys, international flight bookings to Southeast Asia stood at around 38 per cent of pre-pandemic levels, with wide differences between countries: Singapore at around 72 per cent and the Philippines at 65 per cent, but Thailand, where entry rules were then more complicated, at only 24 per cent. Investors stayed positive: in early 2022 JLL forecast that regional hotel investment would exceed US$9 billion that year, up 30 per cent; by mid-year CBRE warned that inflation and interest rates would slow demand for commercial property.
As travel returned, rates in many places rose above pre-pandemic levels. According to Traveloka, by early 2023 average hotel rates across Southeast Asia were more than 10 per cent higher than in 2022, and more than 45 per cent higher in destinations popular with Chinese travellers; Bangkok was up more than 70 per cent and Singapore more than 40 per cent. Across its worldwide system, Marriott International’s average daily rate in the fourth quarter of 2022 was around 13 per cent higher than in the same quarter of 2019.
Three lessons from this period still hold for hotel owners in Vietnam. First, financial plans need scenarios for occupancy, rates and costs; higher rates do not mean that profits have recovered. Second, simple entry rules together with air connectivity are a direct competitive advantage for a destination. Third, in a crisis the management agreement sets the rights and obligations of owner and operator, while negotiation and cooperation decide how well the two come through.

